
The GSD2025 offers a convenient summary of unit-level data and market outcomes – Energy and FCAS markets.
Recently Paul had used it to show how Yallourn Power Station (is) no longer bidding FCAS services (as seen via GSD2025). Alex used it to consider Who killed FCAS?
This article revisits a trend (uncovered a year ago using GSD2024) towards ‘new’ resources dominating FCAS enablement levels. It was true then in 2024, for all but the Raise Regulation market. The trend followed results from 2023 as batteries were emerging and we first included FCAS enablement levels in the GSD.
We find increasing enablement of the ‘new’ resources has only continued, that the new FCAS resources are the dominant providers of all FCAS services nowadays.
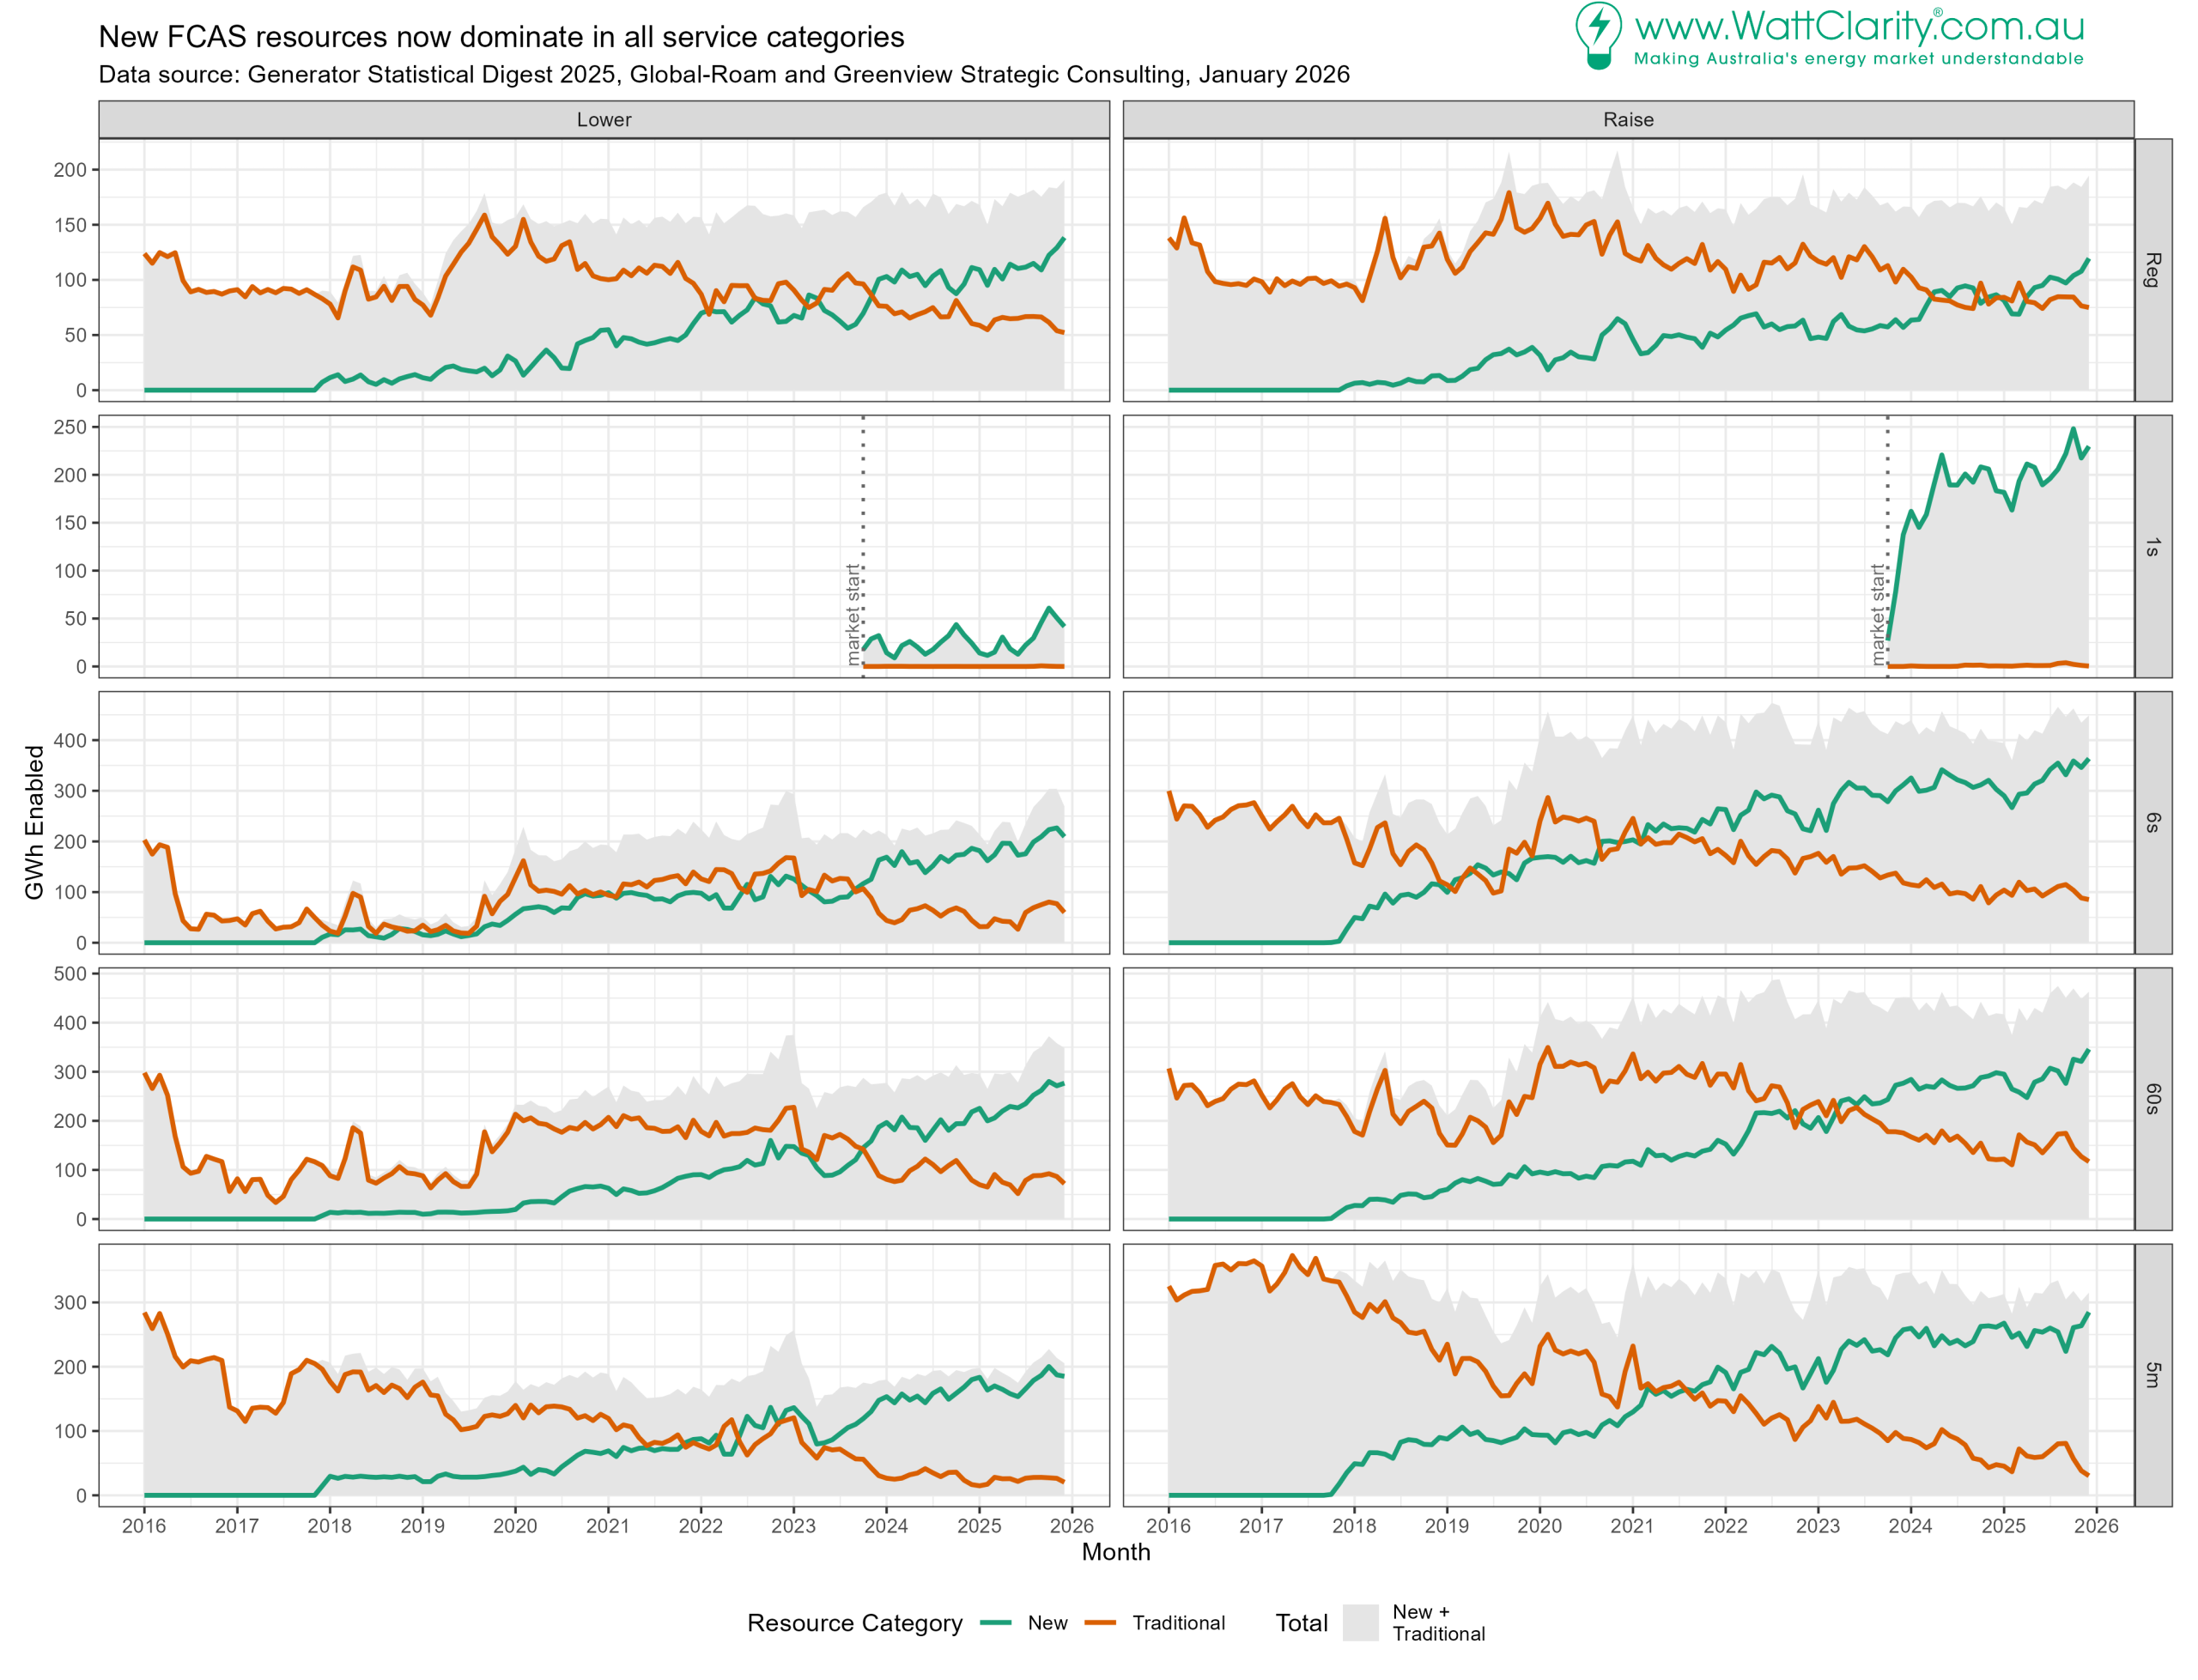
In last year’s article we noted
The ‘new resources’ (group) represents largely inverter-based resources such as grid-scale batteries. It also includes smaller contributions from wind and solar units (where participating) and the newer ancillary service units (such as VPPs).
So this begs a question: “What is the breakdown of resource (fuel) types among that ‘new’ category, is it all batteries?”
We find that (grid-scale) batteries make up the majority. The Electricity fuel type which represents the ancillary service units makes up the remainder, and that is a considerable portion in the Raise markets. However those ancillary service units will, in many cases, also be batteries – just smaller.
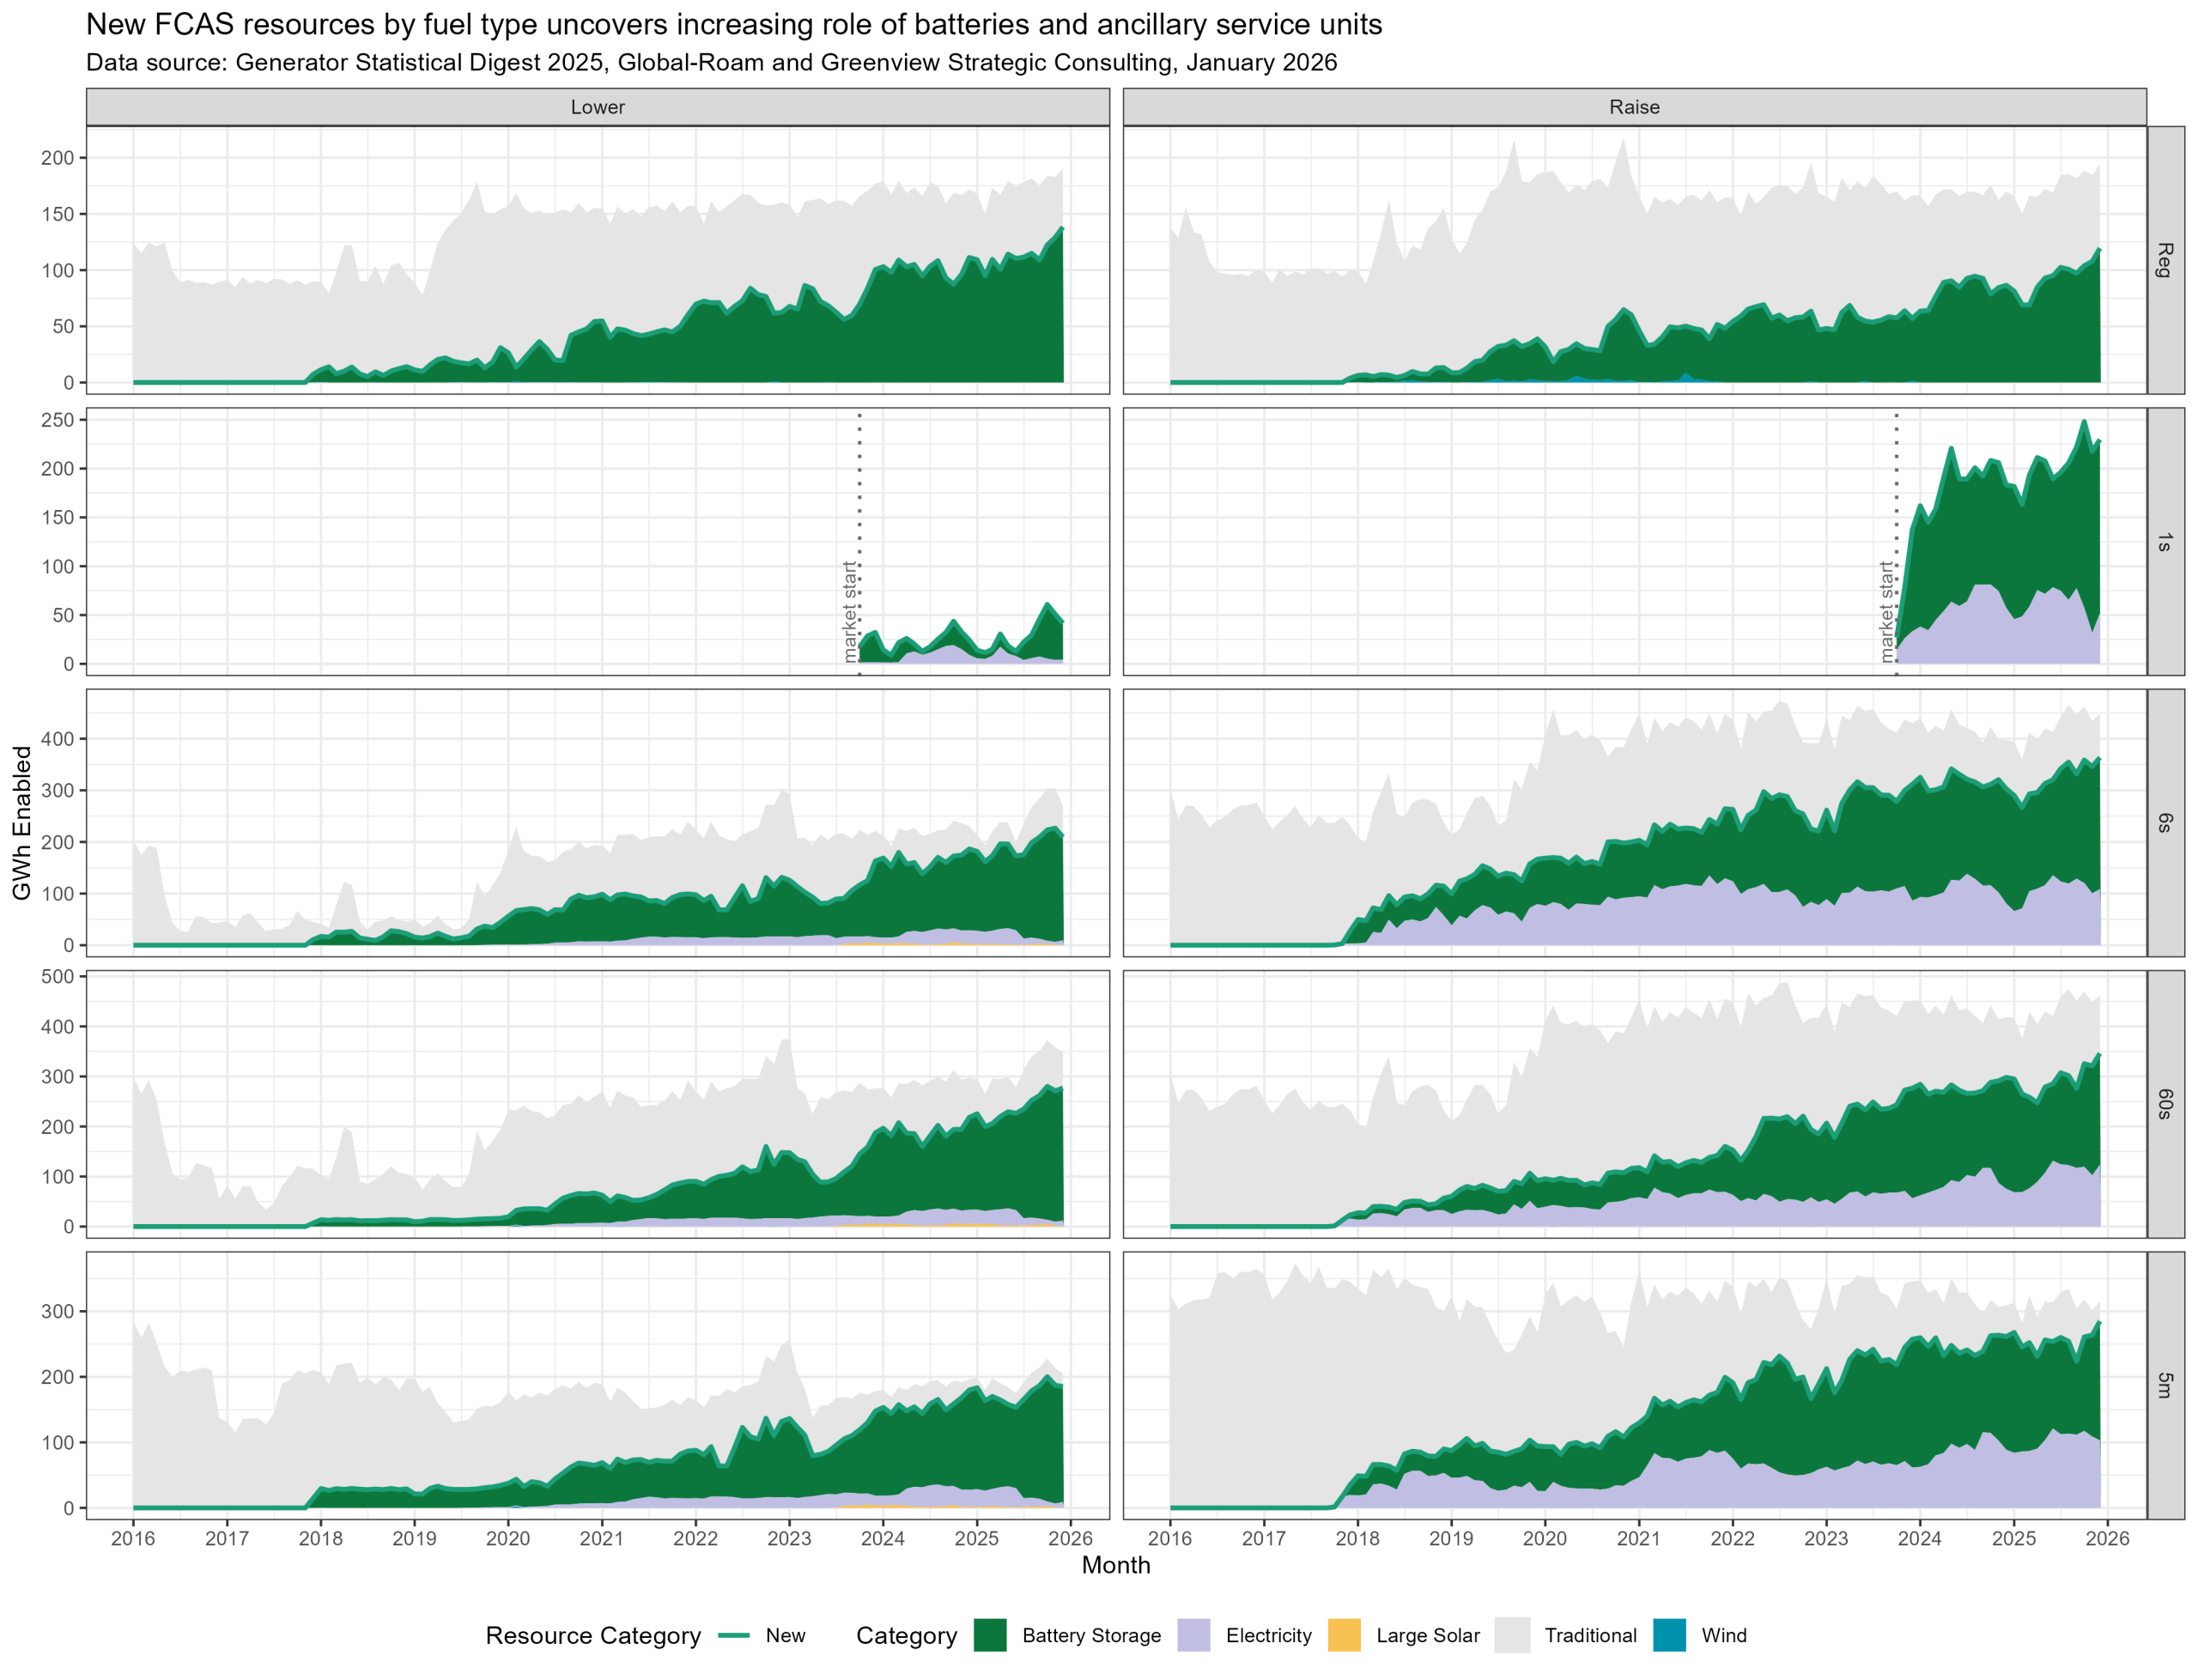
Keen eyes will detect a thin sliver of “Large Solar” enablement in the Lower 6 second, 60 second and 5 minute markets.
While there much month-to-month variability I suspect the level of aggregate enablement for the ‘Electricity‘ units (ancillary service units) will continue to be fairly steady. Increasing deployment of battery storage may see that segment increase its share of the total, offsetting enablement from the Traditional units.
Further detail
Naturally, this is just the tip of the iceberg on understanding the FCAS market outcomes and historical patterns.
A deeper dive that extends the investigation to individual fuel type categories, and bid patterns, and prices and trends of registered capacities:
Where to get the GSD2025
The GSD2025 is available now at this link: GSD2025 + Data Extract.

Be the first to comment on "New FCAS resources dominate enabled levels in 2025"